(FOLEY, Ala.) — On Oct. 7, 2026, I sat down with Baldwin County Revenue Commissioner Teddy J. Faust Jr. at the Revenue Office, 201 E. Section Ave. in Foley, to discuss property tax exemptions and how they affect Baldwin County residents.
Faust began by explaining the importance of property taxes and his office's responsibility to treat residents fairly.
“We're very easy to get along with, and we understand people don't like to pay property tax. I don't like to pay. However, do you enjoy driving down those streets? Do you enjoy the sheriff's department? Do you enjoy public education? My kids are out of school; they were in school. And your father paid, and your grandfather paid. We all paid. That's the way it is. All we care about is to be as fair and equitable as possible and treat everybody the same,” Faust said.
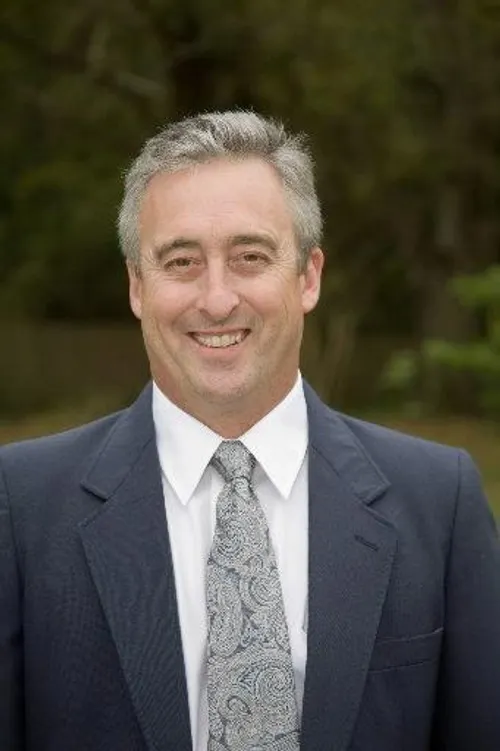
Photo Credit: Baldwin County Revenue Commissioner Teddy J. Faust Jr.
Current-Use Valuation for Agricultural Land
When asked about property tax exemptions for farmland, Faust explained a program known as current-use valuation.
“This type of exemption is called 'current use valuation.' That was designed for timberland, farmland, agricultural pastureland, livestock, and it has morphed into a very loose application of land retention. It's not really well laid out. You can qualify if you have ten acres or more without any real oversight. If it's less than ten acres, we can require somebody to provide evidence that they're raising fruit trees; that's if it's less than ten acres,” Faust said.
He explained that determining whether land qualifies is not always straightforward, particularly when property owners keep animals for personal use rather than agricultural purposes.
“We don't always look at aerial photography and see it's fenced in with horses on it or whatever. Then you get into gray areas where a home with a couple of acres in the back for their horses- those are horses for personal use; it's not business. They're not raising horses. All they're doing is feeding horses and riding them. In areas like that, we don't allow it. So you've got to balance it, and there's a fine line. We've run into instances where somebody qualified for current use years ago, and we've taken it away because it shouldn't have had it,” Faust said.
Editor's note: Current-use valuation is a method of assessing qualifying property rather than a complete tax exemption. Acreage alone does not automatically establish eligibility.
How Is Current-Use Valuation Calculated?
I asked Faust how the exemption is calculated and whether a specific percentage is applied to qualifying property.
“The Department of Revenue does provide the values of the property. Farmlands are so much per acre. They send us a schedule of what the values are per acre for the current year. Please call the office for a current schedule,” he said.
Faust also discussed what happens when agricultural land receiving current-use valuation is sold for development.
“You saw what happened to real estate values in 2007. When a developer buys acreage that has been charged on current use, and they pay significantly more for the acreage than what it was worth as a farm exemption, we do what's called a 'current use rollback.' The farmer was paying far less in property taxes; the developer has to pay the increased value of that acreage for the prior three years,” Faust said.
He explained that the potential rollback amount often becomes part of negotiations between buyers and sellers.
“They have to pay that after the acquisition, and it's usually negotiated in a contract. That's a negotiating point. We often get calls from people that own land and say, 'I've got somebody interested in my property. I'm farming it now. What's the roll back going to be?' So we'll give them an approximation. Then they know how to negotiate. Otherwise, they probably wouldn't have any idea,” he said.
Under Alabama's current-use provisions, rollback taxes may apply when qualifying land is converted to a nonqualifying use.
Who Establishes the Rules?
I asked Faust whether the requirements for agricultural exemptions are established by the county or the Alabama Legislature.
“What I do is governed by the Code of Alabama; the State of Alabama. Everything I do is governed by the Code of Alabama; Title 40 to be precise,” Faust said.
Property tax assessments, classifications, and exemptions are primarily governed by Title 40 of the Code of Alabama, along with applicable state regulations and other relevant laws.
I also asked about smaller properties. For example, if someone owns fewer than 3 acres and wants to grow fruit trees, is there a specific formula or number of trees required to qualify?
“There's a plan. What we look for is a plan: if they have an agricultural plan, and it's in a plot, and if it's surrounded by agricultural property. Just because you plant some orange trees doesn't qualify. Now, if it is a chunk of land and they get out there every year and they get somebody to roll hay up and do that sort of thing, they meet the criteria. And at some point in time, that use is going to change,” Faust said.
He explained that the office considers how the property is used and whether the agricultural activity meets the requirements for current-use valuation.
Homestead Exemptions and the 10-Year Requirement
Our conversation then turned to homestead exemptions, particularly for homeowners age 65 and older.
One question was whether the 10-year residency requirement must be completed at the same property or whether time spent at different qualifying homesteads can be combined.
“Homestead tenure does not need to be accumulated in the same home or even in the same location within Baldwin County — prior homesteads can be aggregated to reach the 10-year threshold,” Faust said.
He also spoke about his father, Joe Faust, and his involvement in legislation concerning senior homeowners.
“My dad, Joe Faust, championed legislation in 2006 that allows, if you're over 65, and if you have had a combined homestead exemption in Baldwin County of 10 years, you get to freeze the value of your property on your homestead,” he said.
The provision allows qualifying senior homeowners to freeze their property's assessed value. However, that does not necessarily mean their total property tax bill will remain unchanged.
Can Property Tax Assessments Go Down?
Another question I raised was whether property assessments ever decrease when real estate values decline.
Faust said his office follows market conditions when determining property values.
“Our obligation is to follow the market. If the market says we need to go up, we go up. If the market says we need to go down, as it did in 2007-08-09, we follow the market. People will say that the property tax never goes down, and I'll say, 'Wait a minute. Let me show you. It does. I have it all charted, twenty years of history, all in spreadsheets, and ready for anybody to see,'” Faust said.
He recalled the real estate market during the years surrounding the housing downturn.
“We were in a market frenzy about that time. People were buying properties left and right. After Hurricane Katrina hit, everything stopped. And that's when you kind of felt the air just fizzling out. It was really the balloon that popped. A couple of years later, you start seeing the people realize, 'Oh my God, I'm upside down,'” he said.
When Does the Commissioner's Next Term Begin?
With the November election approaching, I asked Faust when his next term would begin if he were reelected.
“If I'm elected in November, I'll have been here 18 years. It is a six-year term. A lot of commissioners come and go. The term begins in February 2027,” he said.
A Message to Baldwin County Residents: Before concluding our interview, I asked Faust whether there was anything else he wanted Baldwin County residents to know.
“The biggest thing to me is just to contact us if there are any questions at all about your homestead or anything to deal with property taxes. We're absolutely there for you,” Faust said.
Residents with questions about property tax assessments, agricultural current-use valuation, or homestead exemptions can contact the Baldwin County Revenue Commissioner's Office at 251-937-0245.
Commissioner Faust can also be contacted at tfaust@baldwincountyal.gov.
To provide additional information or request a correction to this report, contact Tracey Gambill at tracey.g@lead4earth.org.
0
0
Comments